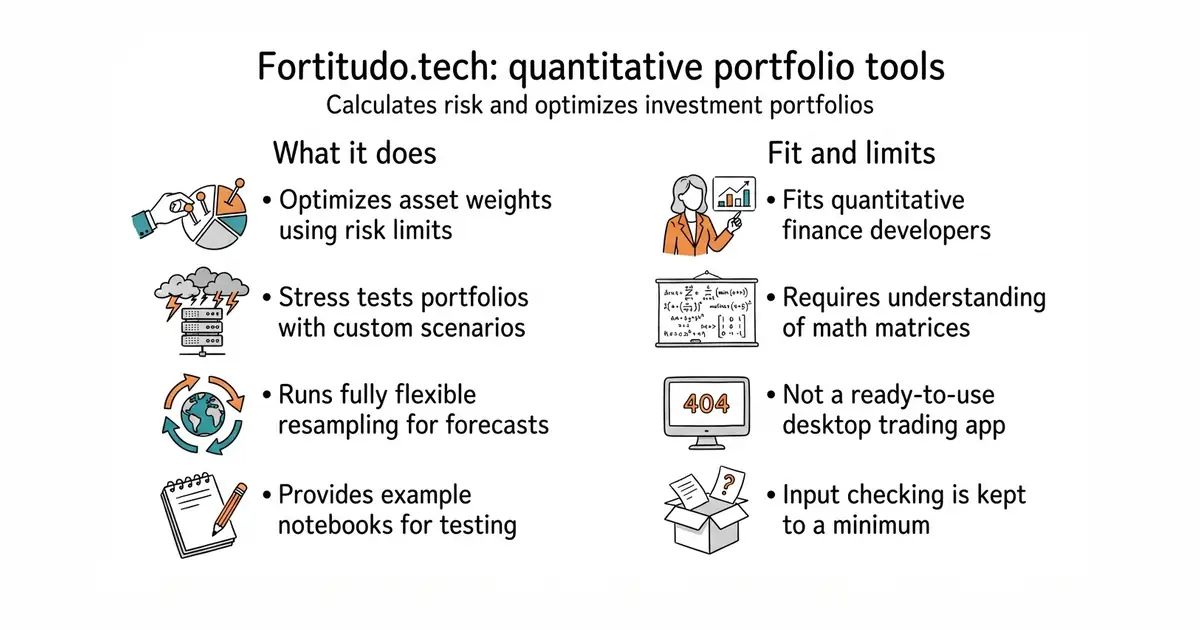
In simple English
Managing a collection of investments involves balancing expected gains against potential losses. Standard tools often fail during sudden market crashes. This library provides advanced mathematical methods to test investment portfolios against extreme stress events. It lets you adjust your holdings based on specific future scenarios and calculated risk limits. You need to write Python code and understand financial matrices to use it.
What it is
A Python package for quantitative finance that combines Entropy Pooling views with Conditional Value-at-Risk optimization and fully flexible resampling. It helps you construct and stress-test investment portfolios using mathematical programming.
What it is good for
Quantitative researchers, algorithmic traders, and financial developers who want to build custom portfolio optimization scripts without paying for expensive commercial risk software.
- Implements advanced portfolio optimization techniques that go beyond basic mean-variance models.
- Includes interactive example notebooks that you can run in the cloud or on your local machine.
- Open-source software licensed under the GPL-3.0 licence, making the core algorithms free to inspect and modify.
- Requires strong programming skills in Python and an academic understanding of quantitative finance.
- Input checking is minimal, so incorrect matrix dimensions or constraints can lead to silent failures or errors.
- Requires external math and optimization libraries like scipy and cvxopt to run properly.
Commercial portfolio risk management software and proprietary asset allocation toolkits.
Python data analysis libraries like pandas and NumPy for processing financial data.
- scikit-portfolio/scikit-portfolio60 stars
A portfolio analysis library built to look and feel like scikit-learn for financial data.

- jesse-ai/jesse8.7k stars
A Python framework for writing crypto trading strategies, testing them against past prices, and running them live.
- hummingbot/hummingbot20k stars
A free framework for writing and running automated trading programs on cryptocurrency exchanges.
- lballabio/QuantLib7.7k stars
The long-established free library for pricing and risk-managing financial instruments.
conda create -n fortitudo.tech -c conda-forge python scipy pandas matplotlib cvxopt
conda activate fortitudo.tech
pip install fortitudo.tech