In simple English
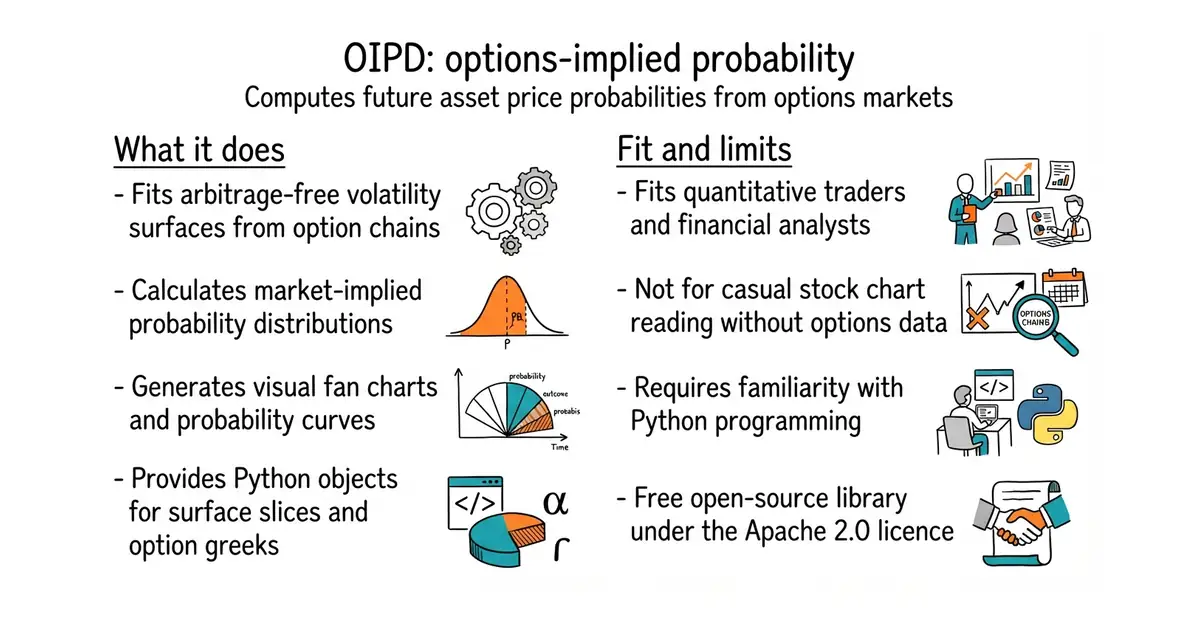
When people buy and sell options on the stock market, their trades carry secret guesses about where prices will go next. This Python library reads those option prices and turns them into a clear probability curve. You can see the exact chance that a stock will go up or down by a certain date. It helps traders look past simple averages and see what the whole market expects. The software is free to download and runs on your own computer.
What it is
OIPD is an open-source Python library that calculates market-implied probability distributions from options data. It takes listed option prices, fits an arbitrage-free volatility surface, and translates that surface into future price probabilities.
What it is good for
Quantitative traders and financial analysts who want to calculate market-implied probabilities and model volatility surfaces without writing complex mathematical formulas from scratch.
- Downloads and fits options data with just a few lines of Python code.
- Includes built-in plotting functions to visualize price fan charts and probability curves.
- Active development with regular releases and an open community.
- Requires a working knowledge of Python and financial mathematics to interpret results.
- Depends on external financial data sources that can change or break.
- Requires local memory to process large multi-expiry volatility surfaces.
Writing custom scripts to calculate implied volatility surfaces and option probabilities from scratch.
yfinance
- quantlib/QuantLib43 stars
QuantLib is a massive C++ library for quantitative finance with Python bindings that also handles options pricing.

- jesse-ai/jesse8.7k stars
A Python framework for writing crypto trading strategies, testing them against past prices, and running them live.
- hummingbot/hummingbot20k stars
A free framework for writing and running automated trading programs on cryptocurrency exchanges.
- lballabio/QuantLib7.7k stars
The long-established free library for pricing and risk-managing financial instruments.
source venv/bin/activate
pip install oipd