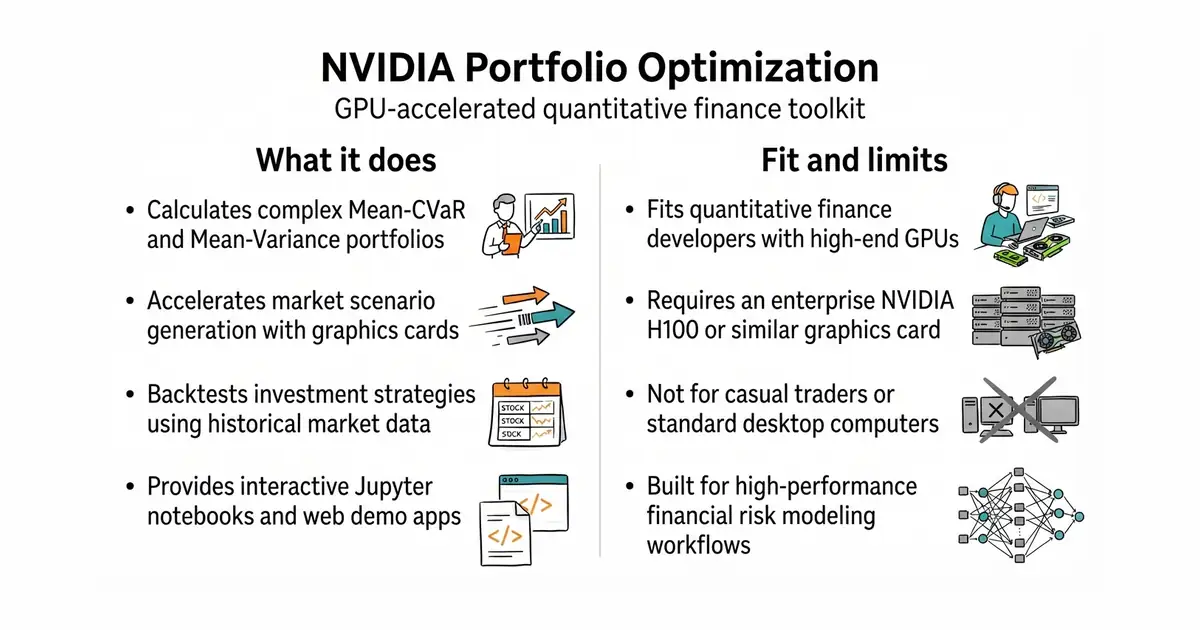
In simple English
This tool helps quantitative finance builders calculate large investment portfolios very quickly. It uses advanced graphics processing cards to run heavy math calculations instead of normal computer chips. You need expensive NVIDIA hardware to run it. It saves hours of waiting when you test trading strategies against historical market data. Financial engineers and researchers use it to speed up their risk models.
What it is
A developer blueprint that combines NVIDIA cuOpt (a GPU-accelerated optimization solver) and RAPIDS cuML (a library for data science and machine learning on GPUs) to run Mean-Variance and Mean-CVaR portfolio calculations.
What it is good for
Quantitative developers and financial modelers who need to run heavy asset allocation simulations and backtest trading strategies without waiting hours for CPU calculations.
- Solves complex portfolio optimization problems up to 160 times faster than standard processors.
- Generates market return scenarios up to 100 times faster using GPU acceleration.
- Includes ready-to-run Jupyter notebooks and a Streamlit interactive demo app.
- Requires an enterprise-grade NVIDIA GPU (such as an H100) with compute capability 9.0 or higher.
- Demands heavy system resources including 32-plus CPU cores and 64 GB of memory.
- Complex setup process inside a specialized Docker container with strict CUDA version dependencies.
Slow CPU-based portfolio optimizers and custom mathematical solver scripts.
NVIDIA cuOpt for high-speed mathematical solving and RAPIDS cuML for GPU data processing.
- NVIDIA/cuopt1.1k stars
The core GPU-accelerated optimization engine that powers this portfolio toolkit.

- jesse-ai/jesse8.7k stars
A Python framework for writing crypto trading strategies, testing them against past prices, and running them live.
- hummingbot/hummingbot20k stars
A free framework for writing and running automated trading programs on cryptocurrency exchanges.
- lballabio/QuantLib7.7k stars
The long-established free library for pricing and risk-managing financial instruments.
docker run --gpus all -it --rm -v ./:/workspace/host --ipc=host -p 8888:8888 -p 8501:8501 nvcr.io/nvidia/pytorch:25.10-py3
git clone https://github.com/NVIDIA-AI-Blueprints/portfolio-optimization.git
cd portfolio-optimization
curl -LsSf https://astral.sh/uv/install.sh | sh
source $HOME/.local/bin/env
uv sync --extra cuda13 --group notebooks
uv run python -m ipykernel install --user --name=portfolio-opt --display-name "Portfolio Optimization"
uv run jupyter lab --no-browser --NotebookApp.token=''