In simple English
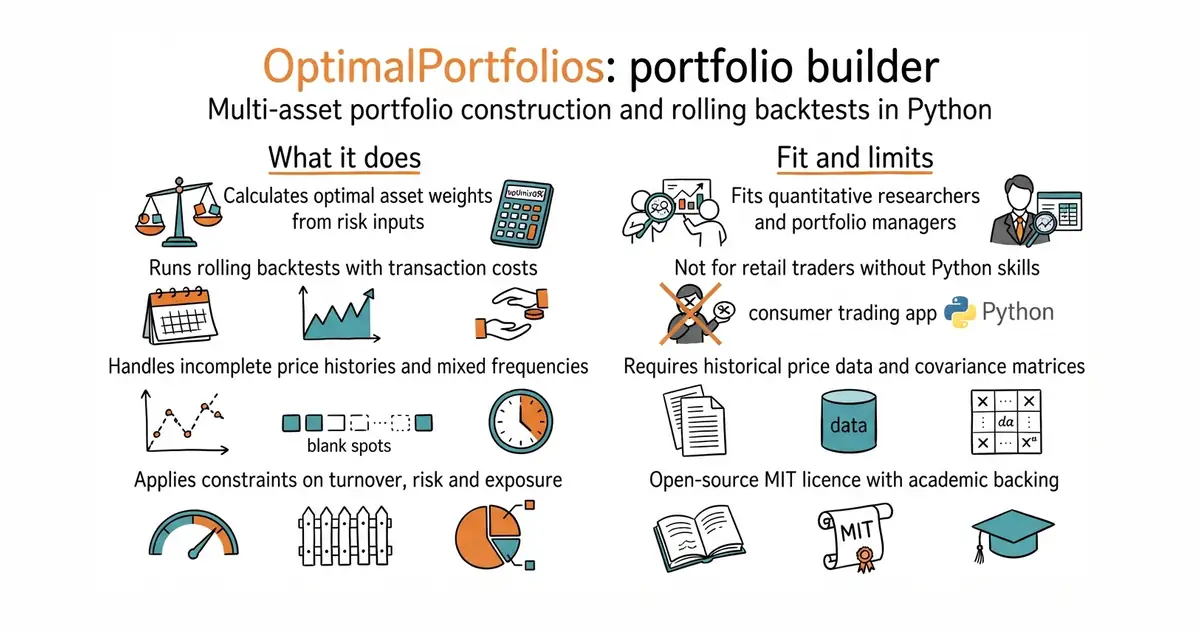
Building a mixed investment portfolio requires balancing asset weights, risks and costs over time. This tool calculates optimal asset weights and runs historical backtests for financial panels. It helps quantitative researchers test allocation strategies without writing complex optimization loops from scratch. The software is free to use under an MIT licence. It requires Python programming knowledge and historical market data to run.
What it is
A Python library for multi-asset portfolio construction and rolling backtesting. It takes covariance matrices and alpha signals to produce constrained target weights and solver outcomes.
What it is good for
Quantitative researchers and portfolio managers who need to build, constrain and backtest multi-asset allocation models with historical price data.
- Handles incomplete histories and mixed rebalancing frequencies across assets.
- Includes drift-aware turnover accounting and transaction cost penalties.
- Backed by published academic research papers in quantitative finance.
- Requires strong proficiency in Python and quantitative finance concepts.
- Relies on external upstream tools for factor model construction.
- Supports quadratic and conic objectives rather than non-quadratic risk measures like CVaR.
Writing custom portfolio optimization and rolling backtest loops from scratch
qis
- jesse-ai/jesse8.7k stars
A Python framework for writing crypto trading strategies, testing them against past prices, and running them live.
- hummingbot/hummingbot20k stars
A free framework for writing and running automated trading programs on cryptocurrency exchanges.
- lballabio/QuantLib7.7k stars
The long-established free library for pricing and risk-managing financial instruments.
pip install optimalportfolios